28 September 2026
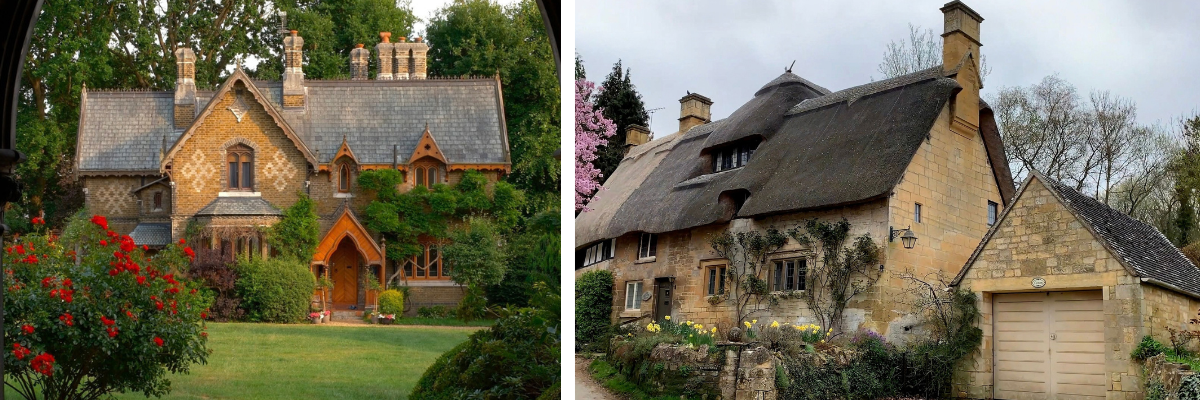
Listed properties come in many forms, from Georgian townhouses, Victorian country homes to centuries-old cottages in rural settings.
For high-net-worth individuals and families, owning a listed property is about more than simply acquiring a unique residence. It means becoming a custodian of Britain's architectural heritage. With that privilege comes a distinct set of responsibilities and risks, particularly when it comes to insurance.
The unique insurance challenges of listed buildings
Unlike modern properties, listed buildings often require specialist materials, skilled craftspeople and traditional construction techniques when repairs are needed. Restoration work may also need to comply with conservation requirements, involve specialist surveys or require approval from local authorities. These factors can significantly increase rebuilding and repair costs compared to a standard property.
While it’s frequently seen with standard and modern homes, underinsurance is particularly prevalent with listed buildings. It’s not uncommon to see a listed property’s rebuild value exceed that of its market value. Listed properties face a higher frequency of underinsurance, alongside a more severe gap in cover.
While establishing the correct sum insured is essential, selecting the right insurer is equally important. Not all insurers are willing to cover listed properties, and some that do, may apply restrictive terms, limits or higher premiums. Understanding which insurers have genuine experience and appetite for heritage and high-value residential properties can make a significant difference.
The value of specialist Private Clients advice
This is where a specialist Private Clients broker may be able to add real value.
Rather than relying on a limited insurer panel or an online quotation process, a specialist broker can present a property's unique characteristics to the most appropriate insurers.
They can help ensure rebuilding costs are accurately assessed and arrange protection that reflects not only the property itself, but also the owner's wider lifestyle, valuables, collections, second homes and other personal assets.
Importantly, a broker can also provide support when a claim occurs. Claims involving listed properties are often more complex, bringing together surveyors, conservation specialists, local authorities and specialist contractors. Having an adviser who understands both the property's requirements and the insurer's expectations can help achieve a smoother outcome when it matters most.
Protecting more than just the property
Many listed properties form part of a wider private client portfolio, alongside high-value contents, fine art, jewellery, watches, collections or additional residences. Taking a holistic approach to insurance helps ensure these assets are protected through a coordinated programme rather than being considered in isolation.
For high-net-worth individuals and families, specialist insurance can make all the difference.
With the right advice and access to experienced insurers, listed properties can be protected appropriately, helping preserve their heritage, character and craftsmanship for future generations.
Information provided is for general guidance only and does not constitute insurance, financial, investment, pension, tax or legal advice. The availability and scope of cover are subject to insurer acceptance, underwriting criteria and policy terms, conditions and exclusions.