20 November 2026
As we navigate through 2026, corporate fleet management is undergoing its most radical transformation in a century.
For commercial operators, the dual transition toward fleet electrification and advanced, tech-driven safety frameworks is no longer a distant horizon; it is the operational reality of today.
Fleet management is no longer just about keeping vehicles on the road; it is about managing complex data ecosystems, navigating entirely new classes of vehicle physics, and rethinking how risk is transferred, mitigated, and insured.
Technological impact on premiums
For many years the commercial fleet insurance world was priced on historical claims frequency , driver demographics and annual mileage. But today undewriters are facing vastly different world where this simplistic view just is not accurate enough an indicator.
The move toward a heavier; more technology laden; larger; electric vehicles (EVs) and then added advanced driver assistance systems (ADAS) has changed how you can gauge the behaviour of a fleet.
The EV cost
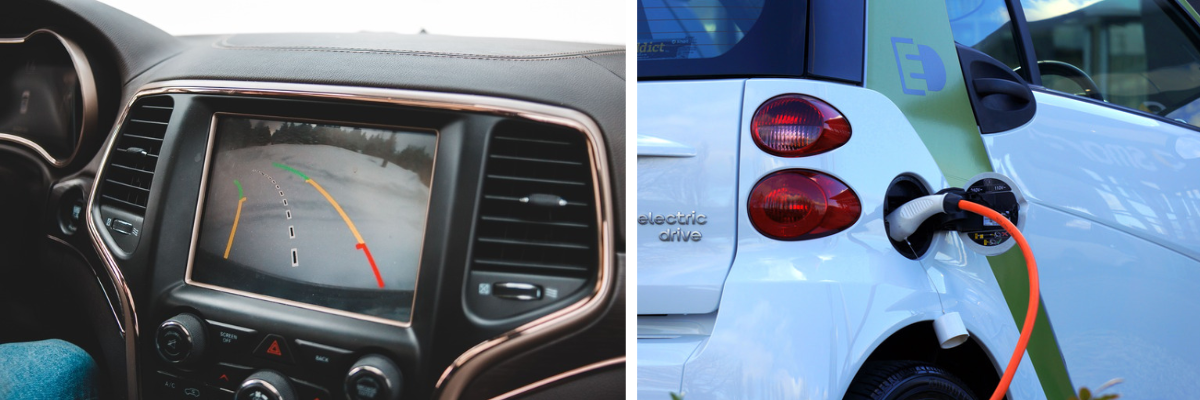
The environmental push toward EVs is clear, the benefits to decarbonising the fleet is well publicised, but it does come at a cost. These vehicles are more of an investment and repair economics are a real influencing factor on average claims costs.
The specialist high-voltage handling knowledge, extended repair times, the parts supply chain complexities; then furthermore, because lithium-ion battery packs can account for a massive share of a vehicle’s total value, minor structural impacts that would have been cosmetic fixes on an ICE vehicle are now frequently considered a total economic loss where the integrity of the battery are in doubt.
The ADAS landscape
Amazing developments in Autonomous Emergency Braking (AEB), lane-keep assist and blind spot monitoring are designed to drastically reduce the low-speed collision frequencies.
However, these are increasing repair times with the need to recalibrate systems post incident.
Anyone that has experienced the complexity of a windscreen claim with ADAS on board will agree that it requires a new time investment at least to have the systems recalibrated. Not only this, there is a need to wait longer for the repair, but there is an expectation for company cars to maintain the audit trail to confirm that they were expertly repaired.
Claims dynamics
The days of simply exchanging insurance details and waiting for a straightforward fault determination are giving way to data-led, high-severity investigations.
Higher Mass and Severity
Electric vans and cars carry heavy battery dead-weight. Physics dictates that higher vehicle mass translates into greater transfer of kinetic energy during a collision. Consequently, insurers are seeing an uptick in the severity of third-party property damage and injury claims.
Thermal Events and "Mixed Injuries"
EV claims occasionally introduce complex exposure scenarios. Beyond standard road trauma, insurers and loss adjusters must account for the specialized handling of damaged high-voltage batteries, including thermal runaway prevention and quarantine protocols.
When toxic fumes or post-collision reignition risks enter the equation, medical causation arguments become multi-layered, extending reserving timelines and increasing legal friction.
Defensibility
Conversely, technology is our greatest ally in claims defence. Telematics, outward- and inward-facing cameras, and real-time event data recorder (EDR) logs mean that liability can often be established instantly.
A prompt First Notification of Loss (FNOL) backed by objective telematics data allows us to control the narrative, curb credit-hire costs, and protect our clients' claims loss-ratios from unmerited inflation.
The wider impact on businesses
For business leaders, fleet risk management directly intersects with corporate governance, environmental, social, and governance (ESG) reporting, and cash flow.
Businesses that fail to adapt their risk management frameworks to accommodate EVs and urban safety compliance (such as London's Progressive Safe System or stringent HGV safety mandates) may face higher insurance costs, reduced insurer appetite or more restrictive policy terms.
Many insurers view proactive risk management favourably. Fleets with limited visibility of driver behaviour or poor maintenance compliance are increasingly facing higher premiums or restrictive policy excesses.
Being able to communicate this to your insurers is a talent in itself, especially today with the complexities of a fleet needs to be presented clearly.
Elevating the safety culture
Technology is shifting safety from reactive punishment to proactive coaching. Modern telematics capture harsh braking, cornering, and distraction markers in real-time. By feeding this data into targeted driver training programs, progressive companies are achieving double-digit reductions in accident frequency.
Partnering for resilience
Managing this transition requires a shift from transactional insurance buying to strategic risk partnership. At Verlingue, our focus is on helping businesses build claims defensibility, integrate telematics insights, and navigate the shifting total cost of ownership of electric fleets. By identifying vulnerabilities before they manifest as losses, we help businesses turn regulatory/market change into a competitive advantage.
Looking Ahead
The shift toward electric and safety-optimized fleets is an opportunity to build leaner, safer, and more sustainable operations. While the complexities around insurance and claims are evolving rapidly, the path forward is clear: proactive data management, rigorous maintenance compliance, and a culture of safety are the ultimate shields for your business.
Chris Moore | Tech IOSH | AIFSM | L3CertFRA
Risk Management Development Director
This article is provided for general information purposes only. Insurance cover, premiums and claims outcomes will depend on individual circumstances and policy terms